Why Selling Your Condo First Could Cost You the House You Want
On the Peninsula, condos and houses move at completely different speeds, and the order you buy and sell decides whether your move-up goes smoothly.
What's Your San Mateo County Home Worth?. Are you thinking of selling your home or interested in learning about home prices in your neighborhood? We can help you.. Discover Market Value
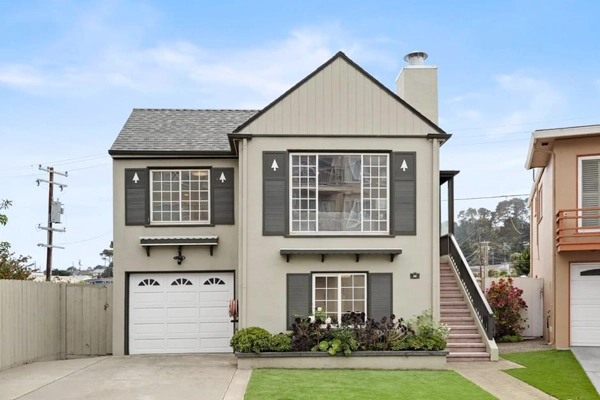
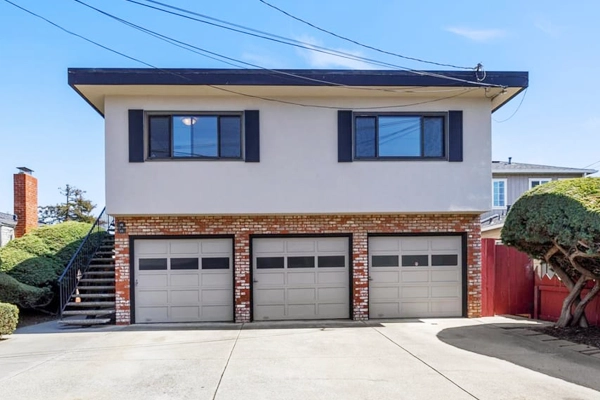
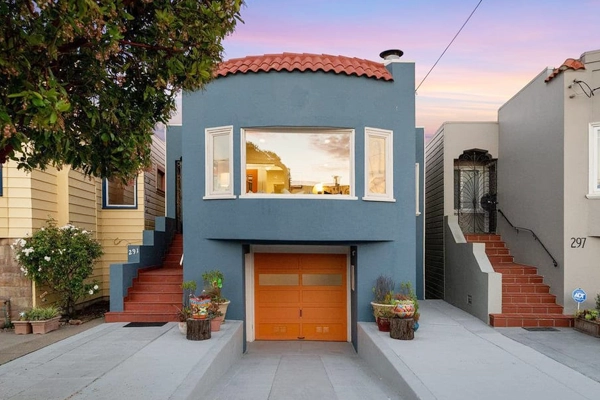
Trading your first condo or townhome for a single-family house is one of the most common moves we help first-time sellers make, and it’s the one where the order of operations matters most.
It comes down to a timing gap.
On the Mid-Peninsula, houses and condos are selling at very different speeds right now, so your sale and your purchase won’t move on the same clock, and treating them as one smooth step is where the plan breaks.
Two markets, two very different speeds. Over the last 30 days, single-family homes on the Mid-Peninsula have sold in about 19 days at 108% of list price, so the typical house goes for more than asking. Condos and townhomes are a different story, averaging around 53 days on the market at about 99% of list price.
A big part of that gap is supply. From March 2025 into the first quarter of 2026, active condo and townhome inventory on the Peninsula climbed roughly 95%, nearly doubling. More choices for buyers mean condos sit longer and face less overbidding, while houses sell fast, often above asking.
The catch for a move-up seller is that you’re playing both sides at once. Your condo competes in the slower, crowded lane, so you have to price it right and show it well from day one. The moment you become a buyer, you’re thrown into the fast, competitive house market.
The three ways to sequence your move. There’s no universally right answer, only the one that fits your cash, your loan, and how much uncertainty you can live with.
Selling first means you list and close the condo, then shop for a house with cash in hand and no sale contingency. That produces a clean, strong offer, exactly what wins in a 19-day house market, but it can leave a gap where you need a short-term rental or a rent-back from your buyer.
Buying first flips it. You lock in the house, then sell the condo, which solves where you’ll live but usually means carrying two mortgages for a stretch. Remember that a condo takes around 53 days to sell, so budget for that much carry, not two weeks.
Lining them up is the third path: selling and buying close together, often with a rent-back or a bridge loan to cover the overlap. It’s the smoothest when it works, but only with a lender and an agent planning it together from the start.
The prep move that surprises first-time sellers. Most people assume the move-up begins when they list the condo. It actually begins weeks earlier, with two things.
First, get your condo fully sale-ready and pre-priced before you write a single offer on a house. In a 53-day condo market, guessing at your equity is dangerous. If you make an offer assuming your condo nets one number and it comes in lower, your whole plan cracks. Knowing your real, market-tested price first means every house decision after that rests on a solid number.
Second, get your financing structured for the overlap, not just a basic pre-approval. Sit down with a lender who can tell you whether you qualify to carry both homes, whether a bridge loan is on the table, and what a rent-back does to your numbers.
The sellers who lose this game fall for a house first and try to reverse-engineer the condo sale to fit. The ones who win prep the sell side quietly in the background, so when the right house appears, they can move at full 19-day speed.
Let’s map out your sequence. The move-up works when you choose your sequence on purpose and prep both your condo and your financing before you fall for a house.
If you own your first condo or townhome and you’re ready to move up, we’d love to help you figure out whether to sell first, buy first, or run them together, based on your actual numbers rather than a guess. Call or text at (650) 274-3598, email at Burt@RealEstateBurt.com, or visit realestateburt.com. Let’s build your move-up plan around real numbers.
-
What's Your San Mateo County Home Worth?. Are you thinking of selling your home or interested in learning about home prices in your neighborhood? We can help you.. Discover Market Value
-
Search All Homes. Search the entire MLS for your next San Mateo County home with pricing, schools, neighborhood data, and more. Search the MLS
-
Free Newsletter. Get our latest Q&A, insights, and market updates to make smarter decisions. Subscribe Now
Frequently Asked Questions
Should I sell my condo before buying a house in San Mateo County?
Not necessarily. Selling your condo first can provide funds for your next down payment, but it may leave you needing temporary housing if you cannot find a suitable home quickly. Buying before selling may help you secure your next property first, depending on your available equity, financing options, and ability to manage two housing payments.
Can I buy a house before selling my condo?
Yes. You may be able to buy a house before selling your condo if you qualify for the new mortgage while still carrying your existing housing expenses. Options may include a bridge loan, a home equity line of credit (HELOC), or qualifying for both mortgages. Your lender can help determine which option fits your financial situation.
What is the risk of selling my condo before finding a new home?
The main risk is selling your condo before securing your next home and then struggling to find a suitable replacement within your timeline. You may need temporary housing, storage, or another move if your home search takes longer than expected. In a competitive market like San Mateo County, planning the timing of both transactions is important.
How can I use my condo equity to buy a house in the Bay Area?
You can use your condo equity toward a down payment by selling the property or, if you qualify, borrowing against its equity through a HELOC or another financing option. The amount available depends on your condo's market value, outstanding mortgage, selling expenses, and lender requirements. Comparing these options before listing can help you plan your next purchase.
How do I coordinate selling a condo and buying a house at the same time?
To coordinate both transactions, start by reviewing your finances with a lender, estimating your condo's selling price and net proceeds, and identifying your next home's budget. You can then explore options such as a contingent offer, a rent-back agreement, or buying before selling. The best approach depends on your financial flexibility, local market conditions, and the timing of both closings.